Benefits and Challenges of Omnichannel Banking for Financial Institutions (2026)
This blog describes the benefits and challenges of omnichannel banking for financial institutions. It explains how connected customer journeys, phased implementation, and measurable outcomes support business growth.
Play Voice
Sitanshu Joshi
Associate Director of Engineering
October 27, 2026
Key Takeaways
- Omnichannel banking connects digital and physical channels, preserving customer information and application progress.
- Connected journeys can improve customer retention, application completion, service efficiency, and relevant cross-selling.
- Legacy systems, fragmented data, security requirements, and organizational silos create significant implementation challenges.
- Banks should prioritize high-impact journeys and validate results through pilots before expanding investment.
- Sustainable returns depend on reliable data, shared accountability, employee adoption, and measurable customer outcomes.
Why Omnichannel Banking Matters for Financial Institutions
An omnichannel banking experience connects digital and physical interactions through shared customer information and workflows. It preserves application progress, service history, and relevant context as customers switch banking channels.
For financial institutions, this continuity helps address fragmented service delivery and disconnected sales processes. Customers can progress between mobile applications, contact centers, and branches without restarting completed steps. Employees can access relevant records and continue servicing requests within established security controls.
Disconnected channels create operational costs through repeated data collection, manual handoffs, and unresolved requests. McKinsey identifies channel complexity as a contributor to higher costs and abandoned customer journeys.
The business priority is connecting these interactions to measurable improvements across the customer lifecycle:
- Revenue: Help customers complete applications and receive relevant offers across connected channels.
- Efficiency: Reduce duplicate processing and give employees visibility into previous customer interactions.
- Retention: Maintain consistent support when customers move between digital services and human assistance.
Achieving these outcomes requires integrated systems, reliable customer data, and clear ownership across teams. Financial institutions must evaluate these requirements alongside implementation costs and expected omnichannel banking ROI before prioritizing their transformation investments.
What Is Omnichannel Banking?
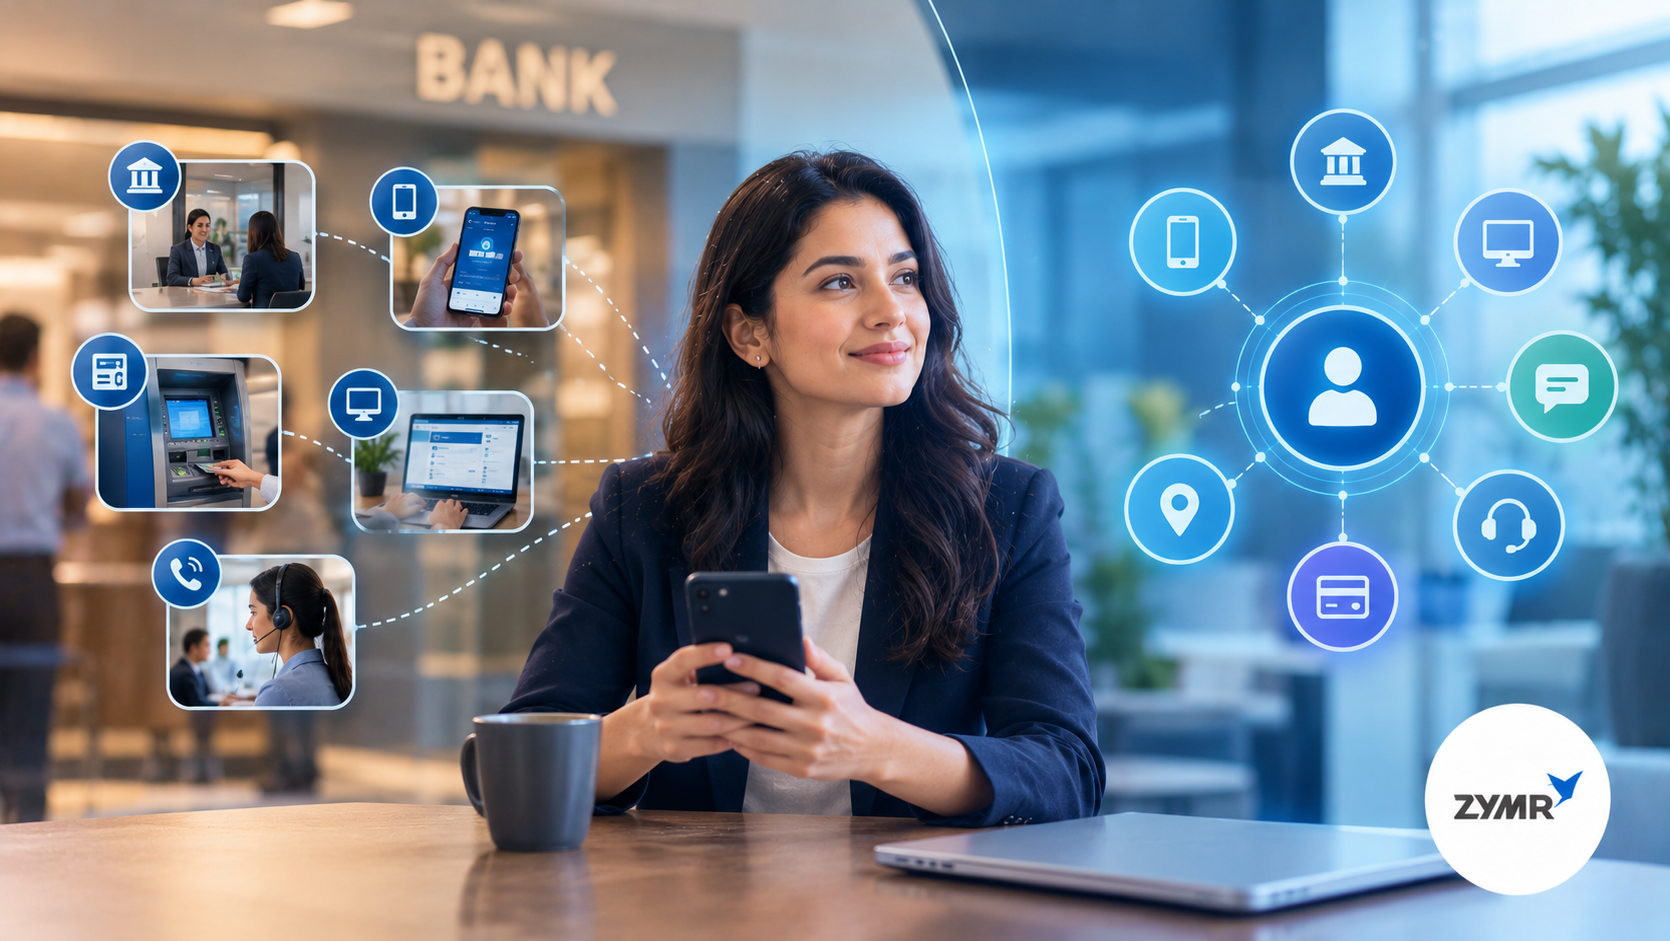
Omnichannel banking integrates mobile, web, branch, and contact center services into connected customer journeys. It allows customers to change channels while retaining relevant information and transaction progress.
For example, a customer starts a loan application online and requests branch assistance. The employee retrieves the saved application and continues processing it, subject to required verification.
Three capabilities support this continuity:
- Shared customer information: Authorized employees and systems access relevant profiles, preferences, and interaction histories.
- Connected workflows: Application status, submitted documents, and service requests remain accessible across supported channels.
- Coordinated service delivery: Digital tools and employees use consistent information to guide the next action.
Multichannel banking provides several service channels that may operate independently. Omnichannel banking connects those channels so customers can continue the same task across them.
This integration requires application programming interfaces (APIs), identity controls, and reliable data synchronization. Banks must also define access permissions and verification requirements for each activity.
The operational objective is continuity: customers retain their progress, while employees receive actionable context. To measure the omnichannel customer experience banking teams deliver, institutions can track completion rates, resolution times, and repeated information requests.
What Are the Key Benefits of Omnichannel Banking?
The benefits of omnichannel banking include connected service, simpler applications, and more informed customer engagement. Business value, and the banking customer experience omnichannel teams deliver, depends on how effectively banks integrate data, workflows, and employee responsibilities.
i. Higher Customer Retention and Loyalty
Consistent service helps customers complete tasks without repeatedly explaining their needs. Preserving context across channels can reduce frustration and support stronger banking relationships.
ii. Increased Cross-Selling and Customer Value
Shared customer information helps banks identify relevant needs across existing products and interactions. Coordinated offers can support additional sales while reducing duplicate or unsuitable outreach.
iii. Better Customer Experience and Satisfaction
In the omnichannel customer experience banking customers increasingly expect, employees can review previous interactions and continue resolving requests when customers change channels. This continuity reduces unnecessary handoffs and gives customers clearer guidance.
iv. Lower Operating Costs and Greater Efficiency
Connected workflows reduce duplicate data entry and manual transfers between service teams. Self-service options also help employees focus on requests requiring specialist assistance.
v. Faster Customer Onboarding and Applications
Saved applications allow customers to resume unfinished steps through another supported channel. Accessible documents and application status reduce avoidable repetition.
vi. Improved Fraud Detection and Risk Management
Combining signals across channels can help banks identify suspicious activity requiring investigation.
vii. Better Support for AI and Personalized Banking
Governed customer data gives AI systems relevant context for recommendations and service assistance.
Building the business case across retention, cross-selling, service efficiency, onboarding, fraud, and AI readiness? Zymr's fintech engineering team helps financial institutions model expected benefits against institution-specific baselines and turn them into a phased digital transformation roadmap.
What Are the Common Challenges of Omnichannel Banking?
Omnichannel banking challenges involve connecting systems, governing customer data, and coordinating delivery across teams. These constraints affect implementation costs, service consistency, and the pace of measurable business improvements.
These challenges require coordinated technical and operational planning. Banks should assess dependencies before committing to delivery timelines or projected omnichannel banking benefits.
Omnichannel Banking Benefits vs. Challenges: What Financial Institutions Should Consider
Financial institutions should compare the benefits of omnichannel banking with integration requirements, operating costs, and delivery risks. Each financial institution omnichannel investment needs a defined customer problem, accountable owner, and measurable success criteria.
Investment priorities within an omnichannel banking strategy should reflect institutional scale, customer needs, and existing technology constraints. Community banks may prioritize onboarding and servicing journeys within available budgets. Larger institutions may need broader coordination across products, regions, and legacy platforms.
Start with a journey where friction, ownership, and baseline performance are clearly documented. Expand after measured improvements justify the implementation and ongoing operating costs.
Weighing these trade-offs for your institution? Zymr engineers the integration layer and modernization path connected journeys depend on, from API-led integration that exposes core banking workflows to application modernization of the legacy platforms behind them.
Examples of Banks Benefiting From Omnichannel Banking
Banks demonstrate connected banking through assisted digital service, integrated financial tools, connected advice, and redesigned physical locations. These examples illustrate specific capabilities and omnichannel banking benefits, not guaranteed returns for every financial institution.
i. Bank of America: Connecting Automated and Human Support
Implementation: Erica provides automated assistance within mobile banking. Mobile Servicing Chat connects customers with live representatives for more complex questions.
Business relevance: This approach gives customers access to human assistance within their digital banking journey. It illustrates how banks can combine routine automation with specialist support.
ii. BBVA: Connecting Digital Interactions With Banker Advice
Implementation: BBVA describes its commercial banking transformation as connecting digital interactions, account manager advice, and financial analysis.
Business relevance: This integration supports coordination between customer engagement and transaction preparation. It demonstrates how connected banking extends beyond consumer apps into business relationships.
iii. Bank of America: Unifying Banking, Investing, and Retirement
Implementation: In 2024, the bank consolidated access across five applications into one personalized digital experience.
Business relevance: Customers can view and manage multiple financial relationships through an integrated platform. This illustrates how institutions can simplify access across previously separate product experiences.
iv. DBS Bank: Redesigning Branches Around Digital Self-Service
Implementation: In 2020, DBS began transforming its Singapore branches with video teller and branch teller machines, supported by on-site digital ambassadors. At the time, more than 95% of regular transactions such as fund transfers, remittances, and bill payments were already completed digitally.
Business relevance: Routine transactions move to self-service, while branch staff concentrate on customers who need assistance. It shows how physical locations can be redesigned to complement digital channels rather than duplicate them.
v. Capital One: Using Physical Locations for Support and Education
Implementation: Capital One Cafés combine fee-free ATMs for checking customers, ambassadors who help with bank and credit card account questions, and free events on savings, credit, and budgeting.
Business relevance: The model gives customers an in-person option for account help and financial education alongside digital banking. It illustrates how institutions can assign a distinct role to each channel within one relationship.
How Financial Institutions Can Overcome Omnichannel Banking Challenges
Financial institutions can address omnichannel banking challenges through phased integration, governed data, and shared accountability. Each improvement should resolve a specific service gap and support a measurable business outcome.
i. Integrate Legacy Systems Incrementally
Use application programming interfaces (APIs) to connect priority workflows with existing banking platforms. Start with a defined journey, such as application tracking, before expanding integration scope.
ii. Establish Reliable Customer Records
Define rules for matching profiles, resolving duplicates, and synchronizing relevant information across systems. Assign data owners to maintain accuracy and manage exceptions before errors affect customers.
iii. Apply Consistent Security Controls
Define authentication, authorization, and verification requirements for each activity across supported banking channels. Preserve useful service context while restricting sensitive information according to employee responsibilities.
iv. Align Teams Around Customer Outcomes
Assign one accountable owner for each journey spanning digital services and assisted channels. Use shared completion and resolution measures to reduce conflicting departmental priorities.
v. Control Costs and Vendor Dependencies
Evaluate integration capabilities, data portability, support obligations, and ongoing charges before selecting platforms. Release funding in stages tied to delivery evidence and demonstrated operational improvements.
vi. Validate Performance Before Expanding
Pilot connected workflows with defined customer groups and train employees handling channel transitions. Compare completion rates, service costs, and errors against documented baselines before broader deployment.
How to Prepare for Omnichannel Banking Transformation
Preparation requires a defined business case, documented system dependencies, and an agreed delivery roadmap. Financial institutions should establish these foundations of their omnichannel banking strategy before selecting platforms or committing to implementation timelines.
i. Identify Priority Customer Journeys
Map where customers abandon applications, repeat information, or encounter delays between service channels. Rank journeys by customer impact, revenue opportunity, service costs, and implementation complexity.
ii. Assess Technology and Data Readiness
Review core systems, integration interfaces, customer records, and identity management capabilities supporting priority journeys. Document data quality gaps, access restrictions, and dependencies that could affect reliable delivery.
Most connected journeys rely on the same capability layers. The platforms below are common examples, not recommendations; selection should follow the readiness assessment and integration requirements.
iii. Build an Institution-Specific Business Case
Estimate implementation costs alongside ongoing licensing, support, training, and maintenance expenses for each initiative. Model expected omnichannel banking ROI using internal baselines and explicit assumptions rather than generic industry benchmarks.
iv. Define Governance and Delivery Responsibilities
Assign business sponsors, journey owners, technical leads, and control teams with clear decision rights. Establish acceptance criteria covering customer continuity, security, accessibility, operational resilience, and employee readiness.
v. Establish a Phased Roadmap
Sequence foundational work, pilot delivery, evaluation, and expansion according to dependencies and available capacity. Set review points where leaders can adjust funding or scope using measured results.
The Future of Omnichannel Banking
Omnichannel banking will likely evolve toward coordinated service across digital tools and human advisers. The pace of omnichannel banking adoption will depend on reliable data, secure integration, and effective oversight of automation.
i. AI-Assisted Service and Advice
AI assistants could use authorized customer context to support requests across connected banking channels. Banks will need clear escalation paths, accuracy checks, and approval controls for consequential actions.
ii. More Proactive Customer Engagement
Connected transaction and service information could help banks identify needs before customers request assistance. Relevant outreach will require appropriate permissions, accurate signals, and controls against unsuitable product recommendations.
iii. Closer Integration With Embedded Finance
Banking journeys may increasingly begin within merchant, accounting, or other third-party business platforms. Preserving application progress and support history will require coordinated interfaces and clear service responsibilities.
iv. More Context for Human Advisers
Digital channels could provide advisers with relevant application details before scheduled consultations begin. This preparation would help specialists focus conversations on unresolved questions and complex financial needs.
v. Greater Emphasis on Journey Performance
Banks may increasingly evaluate service through complete journeys spanning products, teams, and channels. Completion rates, resolution quality, and total service costs can guide investment more effectively than isolated activity counts.
Next Steps
A financial institution omnichannel program should start with one customer journey that has measurable friction and clear business ownership. Use the initial implementation to validate the banking customer experience omnichannel teams deliver, operational readiness, and financial assumptions.
- Select the journey: Choose a process where channel transitions cause delays, abandonment, or repeated work.
- Document baseline performance: Measure completion rates, resolution times, service costs, and customer complaints before implementation begins.
- Define the required continuity: Specify which information, documents, and workflow states must follow customers across channels.
- Assign delivery accountability: Bring business, engineering, operations, and control teams together under one responsible journey owner.
- Pilot and evaluate: Test with a defined customer group and compare results against agreed acceptance criteria.
- Expand using evidence: Approve further investment when measured improvements support the business case and operating model.
Conclusion
FAQs
1. Is omnichannel banking worth the investment for mid-size banks?
>
It can be when priority journeys generate sufficient value to justify implementation and operating costs. Evaluate application completion, service efficiency, and retention opportunities against institution-specific baselines before committing funding.
2. How long does it take to realize omnichannel banking benefits?
>
Timing depends on integration complexity, data readiness, employee adoption, and the selected customer journey. Measure initial improvements after pilot deployment; broader financial returns require sustained adoption and cost tracking.
3. How much does omnichannel banking transformation cost?
>
Costs vary with system dependencies, channel coverage, migration requirements, and the chosen delivery approach. Include integration, licensing, security, testing, training, and ongoing support when estimating total ownership costs.
4. How do banks measure omnichannel banking experience?
>
Track application completion, repeated information requests, channel handoffs, resolution times, and customer satisfaction together. Compare results against baseline performance and segment findings by journey, customer group, and channel transition.
5. What is the future of omnichannel banking in 2028–2030?
>
Likely developments include AI-assisted service, proactive engagement, embedded finance, and more connected human advisory. Adoption will depend on reliable data, secure integration, customer acceptance, and effective oversight of automated decisions.
Have a specific concern bothering you?
Try our complimentary 2-week POV engagement


Our Latest Blogs

October 27, 2026
Benefits and Challenges of Omnichannel Banking for Financial Institutions (2026)
October 23, 2026
Modernizing Legacy Healthcare Systems: Risks, Strategies, and a Phased Roadmap (2026)